Planning an Austin home purchase can feel frustrating when the down payment is only one…
Skip the Air Fryer: Before You Create a Wedding House Fund, Read This
Written by Lesley Guerrero | Chief Operating Officer | Mortgage Loan Originator | NMLS #1615801
Helping Texans make smarter home financing decisions through practical mortgage education.
Wedding season is in full swing, and I’ve noticed something that makes me happy.
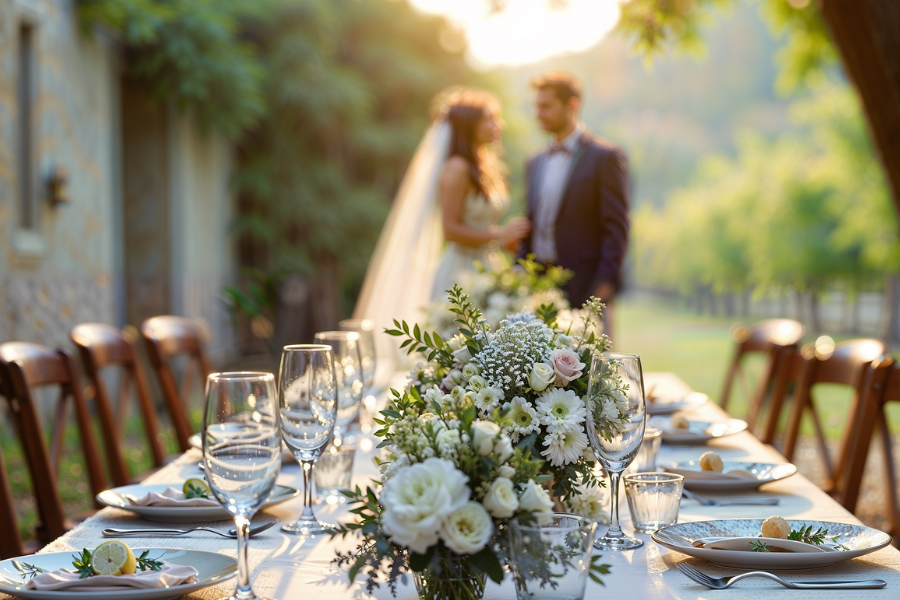
More and more couples are skipping the traditional registry filled with blenders, dish sets, and kitchen gadgets. Instead, they’re asking family and friends to help them save for something much bigger, a home.
Honestly, I think it’s a wonderful idea. If your loved ones want to help you start your next chapter together, contributing toward your future home can be an incredibly meaningful gift.
As a mortgage professional, I love seeing couples think this way.
But before you create a house fund or start accepting contributions, there are a few things I always encourage my clients to consider. A little planning now can make your home purchase much smoother later.
Tip #1: Talk to Your Loan Officer Before You Build the Registry
This is probably my biggest piece of advice.
Every mortgage program has different rules regarding gift funds. Depending on the loan you’re using, documentation requirements can vary, and some loan programs treat wedding gifts differently than others.
A five-minute conversation before the wedding can save hours of paperwork later.
Even if you don’t plan to buy for another six months, it’s worth asking the question now.
Tip #2: Not All Gift Funds Are Created Equal
This is something that surprises a lot of people.
Most mortgage programs have fairly specific rules about who can provide gift funds. Parents, grandparents, siblings and other eligible donors are common examples, but every loan program has its own requirements.
Because you know I love guidelines- Freddie Mac actually has a specific provision for wedding gifts. Unlike traditional gift fund rules, Freddie Mac allows eligible wedding gifts from both related and unrelated people for the purchase of a primary residence, provided the funds are properly documented and deposited within 90 days of the date on your marriage license or certificate.
That’s fantastic news for couples whose friends and extended family want to contribute toward their first home.
Tip #3: Think About Your Paper Trail
One thing newlyweds don’t realize is that lenders aren’t just verifying how much money you have, they’re also documenting where it came from.
Imagine receiving:
- 60 Venmo transfers
- 15 checks
- Cash from your reception
- Contributions through an online registry
- Transfers between multiple bank accounts
None of these are necessarily a problem. But the easier you make the money to trace, the easier your underwriting process usually becomes.
Tip #4: Choose a Registry That Keeps Good Records
If you’re using a home fund platform, spend a few minutes looking at what information it provides.
Can you download transaction reports?
Will it show where the contributions came from?
Can you easily access the information months later if your lender needs it?
Because the lender may need to verify that those deposits are connected to your wedding, keeping good records matters. Registry reports, bank statements and your marriage certificate may all become part of telling the story of where those funds came from.
Tip #5: Keep Things Simple
Whenever possible, I tell clients to avoid moving money from account to account unless there’s a reason to.
If your wedding gifts are deposited into one account, keeping them there often creates a much cleaner financial picture than moving them through multiple checking accounts, payment apps, or savings accounts.
Simple almost always wins.
Tip #6 Don’t Be Afraid to Ask
This may be my least “mortgage” tip, but it might be one of the most important.
I’ve had countless conversations with parents and grandparents who genuinely want to help the next generation become homeowners. Sometimes they’re already planning to contribute. Other times, they’re simply waiting for an invitation or an opportunity to do something meaningful.
If buying a home is one of your first goals as a married couple, don’t be afraid to share that dream with the people who love you. You might be surprised by how many people would rather give a gift that helps you buy your first home than something that ends up in the back of a cabinet.
Every family’s situation is different, and no one should ever feel pressured to give beyond their means. But if homeownership is your goal, simply letting your loved ones know that a house fund is your priority may open the door to conversations that wouldn’t have happened otherwise.
Sometimes, people aren’t waiting to be asked for money, they’re waiting to know how they can help you build the life you’re dreaming about.
Disclaimer: Your milage may vary. Guidelines change. Work with your mortgage professional.
Reviewed: July 2026
Estimated Reading Time: 5 minutes
Topics: Wedding Registry, First-Time Homebuyers, Conventional Loans, FHA Loans, Mortgage Tips, Gift Funds
About the Author
Mission Mortgage of Texas, Inc.
Your mortgage journey begins here. Getting started on the purchase or refinance of your home is just a few minutes away. No commitment needed.
Specializes in: Conventional, FHA, Non-QM
Licensed in: TX
Company NMLS #207583
Related Posts