Building a custom home is exciting, but coordinating the land, construction budget, builder, and mortgage…
Construction Loan Process: What to Expect When Building a Home in Austin
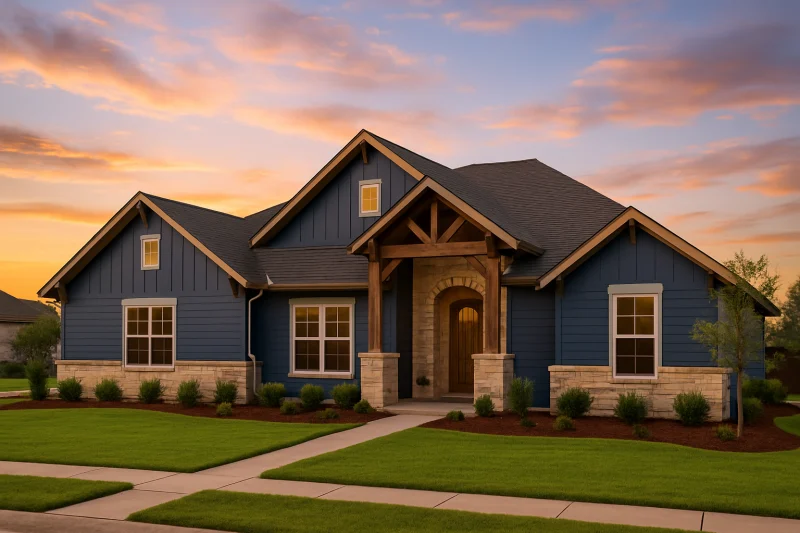
Building your dream home in Austin or surrounding communities can feel like a complex journey, especially when it comes to financing your construction project. A construction loan is a short-term form of financing that covers the cost of building or renovating a home until the work is complete and a permanent mortgage is secured. In this guide, you’ll learn how the construction loan process works, what key steps to expect, and how borrowers in the Austin area can move from blueprint to move-in day.
Key Takeaways
- Purpose: Construction loans finance the building or major renovation of a home, with funds released as work is completed.
- Requirements: Lenders evaluate credit, income, down payment, builder experience, and detailed construction plans.
- Process Timeline: From application to completion, construction loans typically last 12 to 18 months, with periodic draw disbursements.
- Best For: Borrowers building a custom home or undertaking significant renovations in markets like Austin, New Braunfels, or Houston.
Quick Answers: Common Questions About Construction Loans
- How is a construction loan different from a traditional mortgage? Construction loans provide funds needed during the building phase, with draws released as work progresses, then convert (or are replaced) by a traditional mortgage once the home is completed and inspected.
- What do lenders need for approval? Lenders typically require strong credit, proof of income, a qualified builder, and detailed project budgets and timelines.
- Do I make payments during construction? You generally make interest-only payments during the construction phase, based on the funds disbursed (not the full loan amount).
- How are funds released? Draws are disbursed to your builder as key project milestones are completed and verified by inspections.
- Where does Mission Mortgage serve? Mission Mortgage of Texas, Inc. (NMLS# 207583) assists clients across Austin, New Braunfels, the I-35 Corridor, Houston, and beyond.
What Is a Construction Loan?
A construction loan is a short-term, interest-only loan designed to fund the cost of building a home or undertaking major renovations. The lender pays out the funds in stages—called “draws”—as various phases of the construction are finished. Once the home is finished and passes final inspection, the construction loan is typically converted to a permanent mortgage (sometimes called a “construction-to-permanent” or “one-time close” loan) or paid off with a new standard home loan.
These loans are different from standard mortgages because they carry more risk for lenders and require more documentation and oversight. In areas like Austin, Travis County, Williamson County, and growing communities such as Dripping Springs or New Braunfels, construction lending is a valuable option for those who want a truly custom home.
Step-by-Step: The Construction Loan Process in Austin
-
Initial Planning & Documentation
Before applying, gather your plans, blueprints, cost estimates, and finalized contracts with your builder. Lenders want to see a clear building timeline and budget. The builder’s expertise and track record are also critical factors, so working with a local, reputable builder is strongly encouraged. -
Pre-Qualification & Application
Like any mortgage, you’ll complete a loan application and supply documents verifying your credit, income, assets, and liabilities. The team at Mission Mortgage of Texas, Inc. (NMLS# 207583) can walk you through the documentation checklist specific to your project type. -
Loan Approval & Underwriting
Underwriting involves a detailed review of your finances and your construction package—including plans, specs, cost breakdowns, the builder’s credentials, and a value estimate for the finished home. -
Appraisal & Project Approval
An appraiser or inspector reviews the proposed home and construction plans to determine the “as-completed” value. This dictates loan size and may impact required down payment. -
Loan Closing
At closing, you’ll sign documents and pay upfront costs (including down payment and related loan fees). The construction process is now funded and underway. -
Draw Process: Funding the Construction
Rather than a lump sum, your lender releases funds in draws, each linked to completed phases (foundation, framing, etc.). Each draw requires inspection to ensure the stage is finished before more funds are released. -
Interest-Only Payments During Construction
You typically make monthly interest-only payments on the outstanding balance disbursed—meaning payments are lower at the start and rise as more funds are drawn. -
Completion & Conversion to Permanent Financing
Once construction is finished and the final inspection is complete, the loan is either converted automatically to a standard mortgage or paid off by a new long-term loan. If you want a seamless transition, ask about construction-to-permanent loan options.
Construction Loans vs. Traditional Mortgages: Key Differences
| Feature | Construction Loan | Traditional Mortgage |
|---|---|---|
| Use of Funds | Pays for building or major rehab in draws | Pays for move-in ready, completed home |
| Term Length | Short-term (often 12–18 months) | Long-term (usually 15–30 years) |
| Funds Distribution | Incremental draws as work is completed | Lump sum at closing |
| Payments During Build | Interest-only, on funds disbursed | Principal and interest on total amount |
| Approval Requirements | Builder contract, plans, cost breakdown, project timeline | Standard property, basic documentation |
What Do Lenders Look for on a Construction Loan?
Construction lending involves unique risks, so lenders take a detailed approach, often requiring:
- Strong credit profile: Higher credit scores are generally preferred given the project complexity.
- Verifiable income and assets: Full documentation is key, whether you’re a W-2 employee or self-employed using bank statements.
- Reliable builder credentials: The builder’s work history, insurance, and experience are important.
- Detailed plans and specifications: Blueprints, lot details, and a fixed price construction contract.
- Down payment: Generally higher than standard home purchases; minimums vary based on program and lender guidelines.
Local knowledge of the Austin and Texas Hill Country market can help anticipate some requirements. Having an experienced, licensed builder and a clear timeline makes approval smoother.
Construction-to-Permanent Loans: One-Time Close Explained
A common choice for borrowers in Austin is the construction-to-permanent loan (also called “one-time close”). This structure means you apply, qualify, and close only once—for both the construction and permanent loan phases. When your home is finished, the loan automatically converts to a regular mortgage, simplifying costs and paperwork. If you’re interested in this, be sure to ask if your lender offers this option and what guidelines apply. Discover more on our Construction Home Loan program page.
Tips for a Smooth Construction Loan Experience in Central Texas
- Work with a trusted builder: Choose local builders with a strong reputation in the Austin or Hill Country region.
- Solidify your plans early: Last-minute changes to blueprints or costs can cause delays or require re-approval.
- Keep communication open: Regularly check in with your lender, builder, and inspector at each draw stage.
- Plan for delays: Weather, material supply, and labor can impact building timelines. Your lender will explain how draws and interest payments adjust if that happens.
- Get pre-approved early: Starting the pre-approval process with a local lender like Mission Mortgage keeps your project moving and helps set clear expectations from day one.
Who Uses Construction Loans? Real Scenarios in Austin and Beyond
Construction loans are most common for:
- Borrowers building a custom home on their own land in Travis or Williamson County
- Clients purchasing tear-downs in established neighborhoods of Austin and rebuilding new homes
- Move-up buyers constructing a larger home in growing areas like Georgetown, Leander, or Dripping Springs
- Self-employed borrowers looking for flexible ways to document income for unique home designs
The flexibility of construction lending opens the door for many homebuyers, but it’s especially valuable for those who want a tailored space or have land ready to build on.
Connect With Local Experts for Your Austin Construction Loan
If you’re considering building a home anywhere in Austin, New Braunfels, the I-35 Corridor, Houston, or nearby regions, starting with a conversation about goals and budget can prevent surprises. Our team is here to help you review scenarios, compare construction and permanent financing options, and plan your next steps. Thinking about pre-approval? Call, text, or email us—we’re ready to answer your questions about the construction loan process and get you one step closer to your new home.
Frequently Asked Questions
How much down payment do I need for a construction loan?
Down payment requirements for construction loans are generally higher than for traditional mortgages. Minimums can vary widely based on lender, borrower, and project specifics, but often start at 10%–20%. Always check current guidelines and lender requirements for your scenario.
Can I use a construction loan for renovations?
Yes, certain construction loan programs support major renovations or rebuilding existing homes, as long as an approved contractor and detailed plans are provided. The scope of work and your property's “after renovation value” are key factors for eligibility.
What happens if construction takes longer than planned?
Delays can happen due to weather, supply chain issues, or project changes. If construction goes beyond the original loan timeline, you may be able to request a loan extension, but additional fees or higher interest costs may apply. Always communicate early with your lender if delays are expected.
Do I need a separate loan for the land?
If you already own the land, its value may count toward your down payment. If you're buying land and building at the same time, a construction loan can sometimes cover both, depending on lender guidelines and whether the land is purchased simultaneously or already owned.
Will my rate be the same on the permanent mortgage?
With construction-to-permanent loans, you may lock in your permanent rate upfront. However, rates on separate construction and permanent loans may differ, depending on market conditions at each stage. Discuss current options and rate-lock timing with your lender before you proceed.
This is educational and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.
About the Author
Mission Mortgage of Texas, Inc.
Your mortgage journey begins here. Getting started on the purchase or refinance of your home is just a few minutes away. No commitment needed.
Specializes in: Conventional, FHA, Non-QM
Licensed in: TX
Company NMLS #207583
Related Posts