Choosing between a jumbo mortgage and a conventional conforming mortgage can be confusing when the…
How We Evaluate Construction Loan Options for Building a Home in Austin
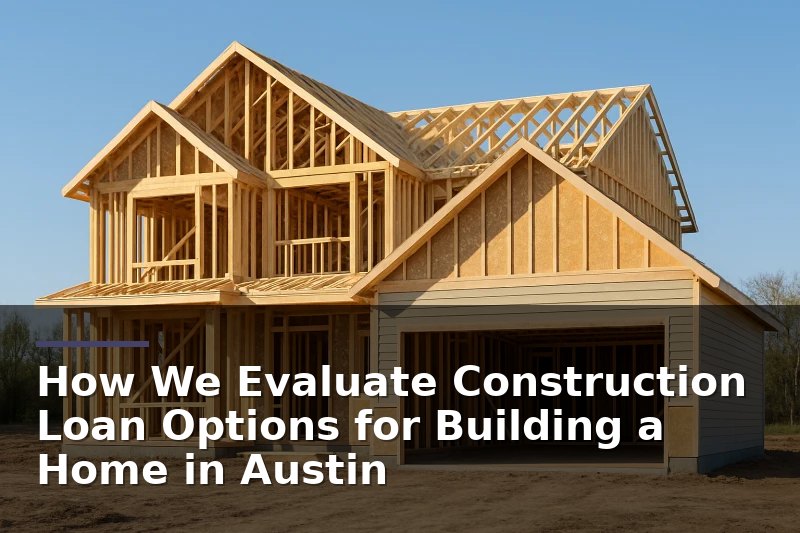
Building a home in Austin can be exciting, but comparing construction financing, builder requirements, budgets, and timelines can quickly become overwhelming. We evaluate construction loan options by reviewing the borrower’s finances, the property and plans, the builder, the total project budget, and the loan’s conversion to permanent financing. In this guide, we at Mission Mortgage of Texas, Inc. (NMLS# 207583) explain how we assess these factors and help borrowers compare practical paths forward.
Key Takeaways
- Loan Structure: Construction financing may use one closing or separate construction and permanent loans.
- Project Review: The lender typically evaluates the plans, specifications, builder, budget, appraisal, land, and construction schedule.
- Borrower Requirements: Credit, documented income, available funds, existing debts, and financial reserves all affect the available options.
- Timeline: Approval must account for both underwriting and project review, so construction loans commonly take longer to prepare than standard purchase mortgages.
- Best For: These loans may fit borrowers building a primary residence, second home, or eligible investment property, depending on the program.
Quick Answers About Austin Construction Loans
- How is a construction loan different from a regular mortgage? Funds are generally released in stages as work is completed rather than paid out in one lump sum at closing.
- Can land equity help with the financing? Often, yes. Eligible equity in a lot you already own may count toward the required borrower contribution, subject to the appraisal and program guidelines.
- When do construction loan payments begin? Payments typically begin during construction and may be based on the amount drawn, but the payment structure varies by loan.
- Can a self-employed borrower obtain a construction loan? Potentially. Qualification depends on documented income, credit, liquidity, project details, and the guidelines of the selected program.
We Start With the Entire Building Plan, Not Just the Interest Rate
A construction loan is both a mortgage decision and a project-risk decision. A competitive rate may not be useful if the loan does not fit the construction schedule, builder contract, draw process, or borrower’s long-term plans.
We begin by identifying what the borrower is trying to accomplish:
- Buy a lot and build immediately
- Build on land already owned
- Replace an existing structure with a new home
- Finance a custom or semi-custom home
- Complete a major renovation that may require a different loan structure
- Build a higher-value property that may require jumbo financing
For a broader explanation of available structures, borrowers can review our construction home loan options. The right structure depends on the complete scenario rather than any single feature.
One-Time Close vs. Two-Time Close Construction Financing
One of our first decisions is whether a one-time close or two-time close structure makes more sense. Availability varies by lender, loan program, property type, and project.
| Feature | One-Time Close | Two-Time Close |
|---|---|---|
| Closings | Construction and permanent financing are arranged through one closing. | The construction loan and permanent mortgage close separately. |
| Rate Planning | May establish the permanent financing terms before construction begins. | Permanent financing is arranged closer to project completion at then-current terms. |
| Qualification | Usually underwritten for the construction and permanent phases upfront. | May require qualification for a new permanent mortgage after construction. |
| Flexibility | Can simplify closing but may offer less flexibility if plans change. | May allow more permanent-loan choices later, with added refinancing risk and costs. |
A one-time close can reduce the uncertainty of arranging a second loan, while a two-time close may provide more flexibility after the home is complete. We compare closing costs, qualification requirements, rate-lock provisions, extension policies, and the possibility that the borrower’s finances or market conditions could change during construction.
How We Review the Borrower’s Financial Position
Construction underwriting commonly looks beyond the standard income, asset, and credit review used for an existing home. The lender must determine whether the borrower can support the project through completion, including unexpected costs or delays.
Income and employment
For salaried borrowers, documentation may include pay statements, W-2s, tax returns when required, and employment verification. For self-employed borrowers, the review may involve personal and business tax returns, year-to-date financial statements, business bank statements, and verification that the business remains active.
Some borrowers with strong cash flow but significant tax deductions may explore a bank statement program. These are generally non-QM loans with different pricing, down payment, reserve, and documentation requirements. Not every alternative-income program permits construction financing, so program availability must be confirmed early.
Existing housing obligations
If the borrower will keep making payments on a current home while construction is underway, those obligations may be included in the debt-to-income analysis. We look at whether the borrower plans to sell, retain, or rent the existing property and what documentation the selected program requires.
Cash, reserves, and contingency funds
Borrowers may need funds for the down payment, closing costs, prepaid expenses, builder deposits, items outside the contract, and reserves. A lender may also require a construction contingency in the budget.
Reserves matter because cost changes and schedule delays can occur even with a detailed contract. Funds required to close are different from post-closing reserves, and both should be reviewed before a borrower commits to a project.
How the Lot and Land Equity Affect the Loan
If the borrower already owns the lot, we review its current value, any outstanding liens, the purchase date, and how the land was acquired. Depending on the loan program, eligible land equity may reduce the cash needed at closing.
If the lot is being purchased as part of the transaction, the lender reviews the purchase contract and determines how the land cost fits into the total project. Certain site expenses—such as utility connections, grading, drainage, engineering, or access work—may need to be included in the construction budget.
Austin-area projects can differ substantially by location. A build in Travis County may involve different permitting, utility, topography, and site-preparation considerations than a property in Hays, Williamson, or Bastrop County. Hill Country lots can also require added attention to slope, rock, septic systems, wells, and access.
How We Evaluate the Builder, Contract, and Budget
The lender typically must approve the builder before construction begins. This is not the same as recommending or guaranteeing a builder’s performance. It is a financial and operational review designed to confirm that the builder and project meet the lender’s eligibility standards.
Builder documentation may include:
- Business and contact information
- Applicable insurance and licensing documentation
- Experience with similar projects
- References or completed-project history
- A signed construction contract
- Detailed plans, specifications, and cost breakdown
- A proposed construction schedule
We also review whether the contract is fixed-price, cost-plus, or another structure. A detailed budget matters because the lender’s draw process is based on completed work and documented project costs. Vague allowances or missing site expenses can create funding gaps later.
The Construction Appraisal Looks at the Completed Home
A construction appraisal generally evaluates the property based on the plans, specifications, lot, and expected completed condition. The appraiser uses available comparable sales and market data to develop an opinion of the completed value.
The lender may calculate financing using the project cost, appraised value, or a program-specific combination of both. If the appraisal is lower than expected, the borrower may need to modify the plans, contribute additional funds, renegotiate costs, or consider another structure.
This can be especially relevant for highly customized homes, luxury neighborhoods, rural properties, and areas with few comparable sales. For projects above conforming loan limits, we may also evaluate jumbo home loan options, which can have additional reserve, appraisal, and underwriting requirements.
How Construction Draws and Inspections Work
Construction funds are generally held by the lender or a draw administrator and released in stages. The builder submits a draw request after reaching a defined construction milestone. An inspection may then confirm the percentage of work completed before funds are released.
Common draw stages may include site work, foundation, framing, mechanical systems, drywall, finishes, and final completion. The exact schedule depends on the lender and construction contract.
Borrowers should ask about:
- How draw requests are submitted
- Who orders and pays for inspections
- How quickly approved draws are funded
- Whether retainage is held until completion
- How change orders are handled
- What happens if construction exceeds the original term
Draw procedures affect the builder’s cash flow and the borrower’s experience. We want the builder to understand the process before closing rather than discovering funding requirements after work begins.
Program Guidelines and Lender Overlays Are Not the Same
Construction financing may be available through conventional, FHA, VA, jumbo, portfolio, or non-QM channels. Each channel has its own borrower and property requirements, but individual lenders may also impose overlays.
For example, a program may permit a certain property type while a particular lender does not offer construction financing for that property. A lender may also require higher reserves, stronger credit, a specific builder profile, or a shorter construction period than the underlying program requires.
As of 2026, products and overlays continue to vary considerably. Rates, fees, minimum contributions, draw policies, and qualification standards should be verified for the specific borrower and project.
Our Step-by-Step Evaluation Process
- Define the project. We identify the property use, lot status, home design, estimated cost, builder, and desired timeline.
- Review borrower qualifications. We examine income documentation, credit, debts, assets, reserves, and the current housing situation.
- Estimate the total cash requirement. This includes the borrower contribution, closing costs, reserves, and expenses outside the financed budget.
- Compare loan structures. We assess one-time and two-time close options, permanent financing terms, and relevant conventional, government, jumbo, or non-QM possibilities.
- Review the project package. Plans, specifications, contracts, allowances, site costs, and builder documentation must align.
- Plan for appraisal and underwriting. We discuss how the completed value and lender guidelines may affect the maximum financing.
- Confirm draw and completion requirements. Before closing, the borrower and builder should understand inspections, draw timing, change orders, and extension rules.
Plan the Financing Before Finalizing the Build
The most useful time to review construction financing is before paying large nonrefundable deposits or finalizing a contract. Early planning can reveal whether the proposed budget, allowances, and timeline are compatible with the available loan structures.
If you are considering a build in Austin, along the I-35 Corridor, New Braunfels, San Antonio, Houston, or elsewhere in Texas, we invite you to call, text, or email us. We can review your scenario, compare available options, and explain the documentation and pre-approval planning that may be needed before you move forward.
Frequently Asked Questions
What happens if construction costs exceed the approved budget?
Cost overruns are not automatically added to the loan. The borrower may need to use contingency funds or other verified assets, and material changes may require lender approval, revised plans, or a new appraisal.
Can I change builders after the construction loan closes?
A builder change generally requires lender approval and may involve a new contract, budget review, insurance documentation, and revised completion schedule. The change could delay draws, so borrowers should contact the lender before ending or replacing a builder agreement.
What if the completed appraisal is lower than the project cost?
The lender may base financing on the applicable program calculation using cost and appraised value. A shortfall could require more borrower funds, budget revisions, contract changes, or a different loan option.
Can an owner-builder qualify for construction financing?
Some programs may allow owner-builders, but many lenders require an independent qualified builder or restrict transactions involving the borrower’s business. Eligibility depends on experience, licensing where applicable, project controls, and lender overlays.
What happens if the home is not finished before the construction term expires?
The lender may offer an extension, but approval is not automatic and additional fees, documentation, or underwriting may apply. We recommend discussing delays as soon as they arise so the borrower and builder can evaluate the available options.
This is educational and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.
About the Author
Mission Mortgage of Texas, Inc.
Your mortgage journey begins here. Getting started on the purchase or refinance of your home is just a few minutes away. No commitment needed.
Specializes in: Conventional, FHA, Non-QM
Licensed in: TX
Company NMLS #207583
Related Posts